“From Russia, with love.” This may well have been one of October’s defining phrases. FBI Director Kash Patel used the words in a post on X in response to an inaccurate report by MS NOW. Evoking a James Bond film, the phrase also came at a pivotal moment in U.S.-Russia energy relations.
Washington’s sanctions policy toward Russian energy products, along with the scope for diesel trade, offers a different perspective from which to interpret the remark. In particular, the sanctions legislation targeting Russia, adopted in September, formed part of Washington’s efforts to increase economic pressure on Moscow. However, the September legislation and the diesel license issued in October should not be treated as parts of the same legal mechanism.
New steps, questions
The main U.S. ban on imports of Russian fossil fuels was introduced under the Ending Importation of Russian Oil Act, which took effect on April 8, 2022. Sanctions against Russian energy companies were subsequently expanded. In this context, the Lindsey O. Graham Sanctioning Russia and Iran Act of 2026, signed by U.S. President Donald Trump on Sept. 18, 2026, represents a continuation of efforts to restrict Russia’s energy revenues.
Sanctions legislation and executive branch licenses authorizing specific transactions are distinct legal instruments. To assess the impact of the September legislation on Russian energy trade, it is necessary to examine separately which provisions target direct imports and which address trade with third countries or sanctions circumvention. The official text of the 2022 import ban is a key reference for understanding this distinction.
On Oct. 9, 2026, the U.S. Department of the Treasury’s Office of Foreign Assets Control (OFAC) issued General License 135, authorizing transactions involving Russian-origin diesel fuel. Subject to specific conditions, the license permits transactions related to the sale, delivery, unloading from vessels, and importation into the United States until April 7, 2027. This general license allows certain categories of transactions that would normally be prohibited under U.S. sanctions regulations, subject to specified conditions. However, this authorization does not mean that sanctions on all Russian energy products have been lifted.
The key legal question is how the authorization granted by OFAC under its own sanctions rules can be reconciled with a separate federal import ban enacted by Congress. Beyond the legal framework, the extent to which the announced supply volumes will materialize and how much additional supply they will bring to the market also matter.
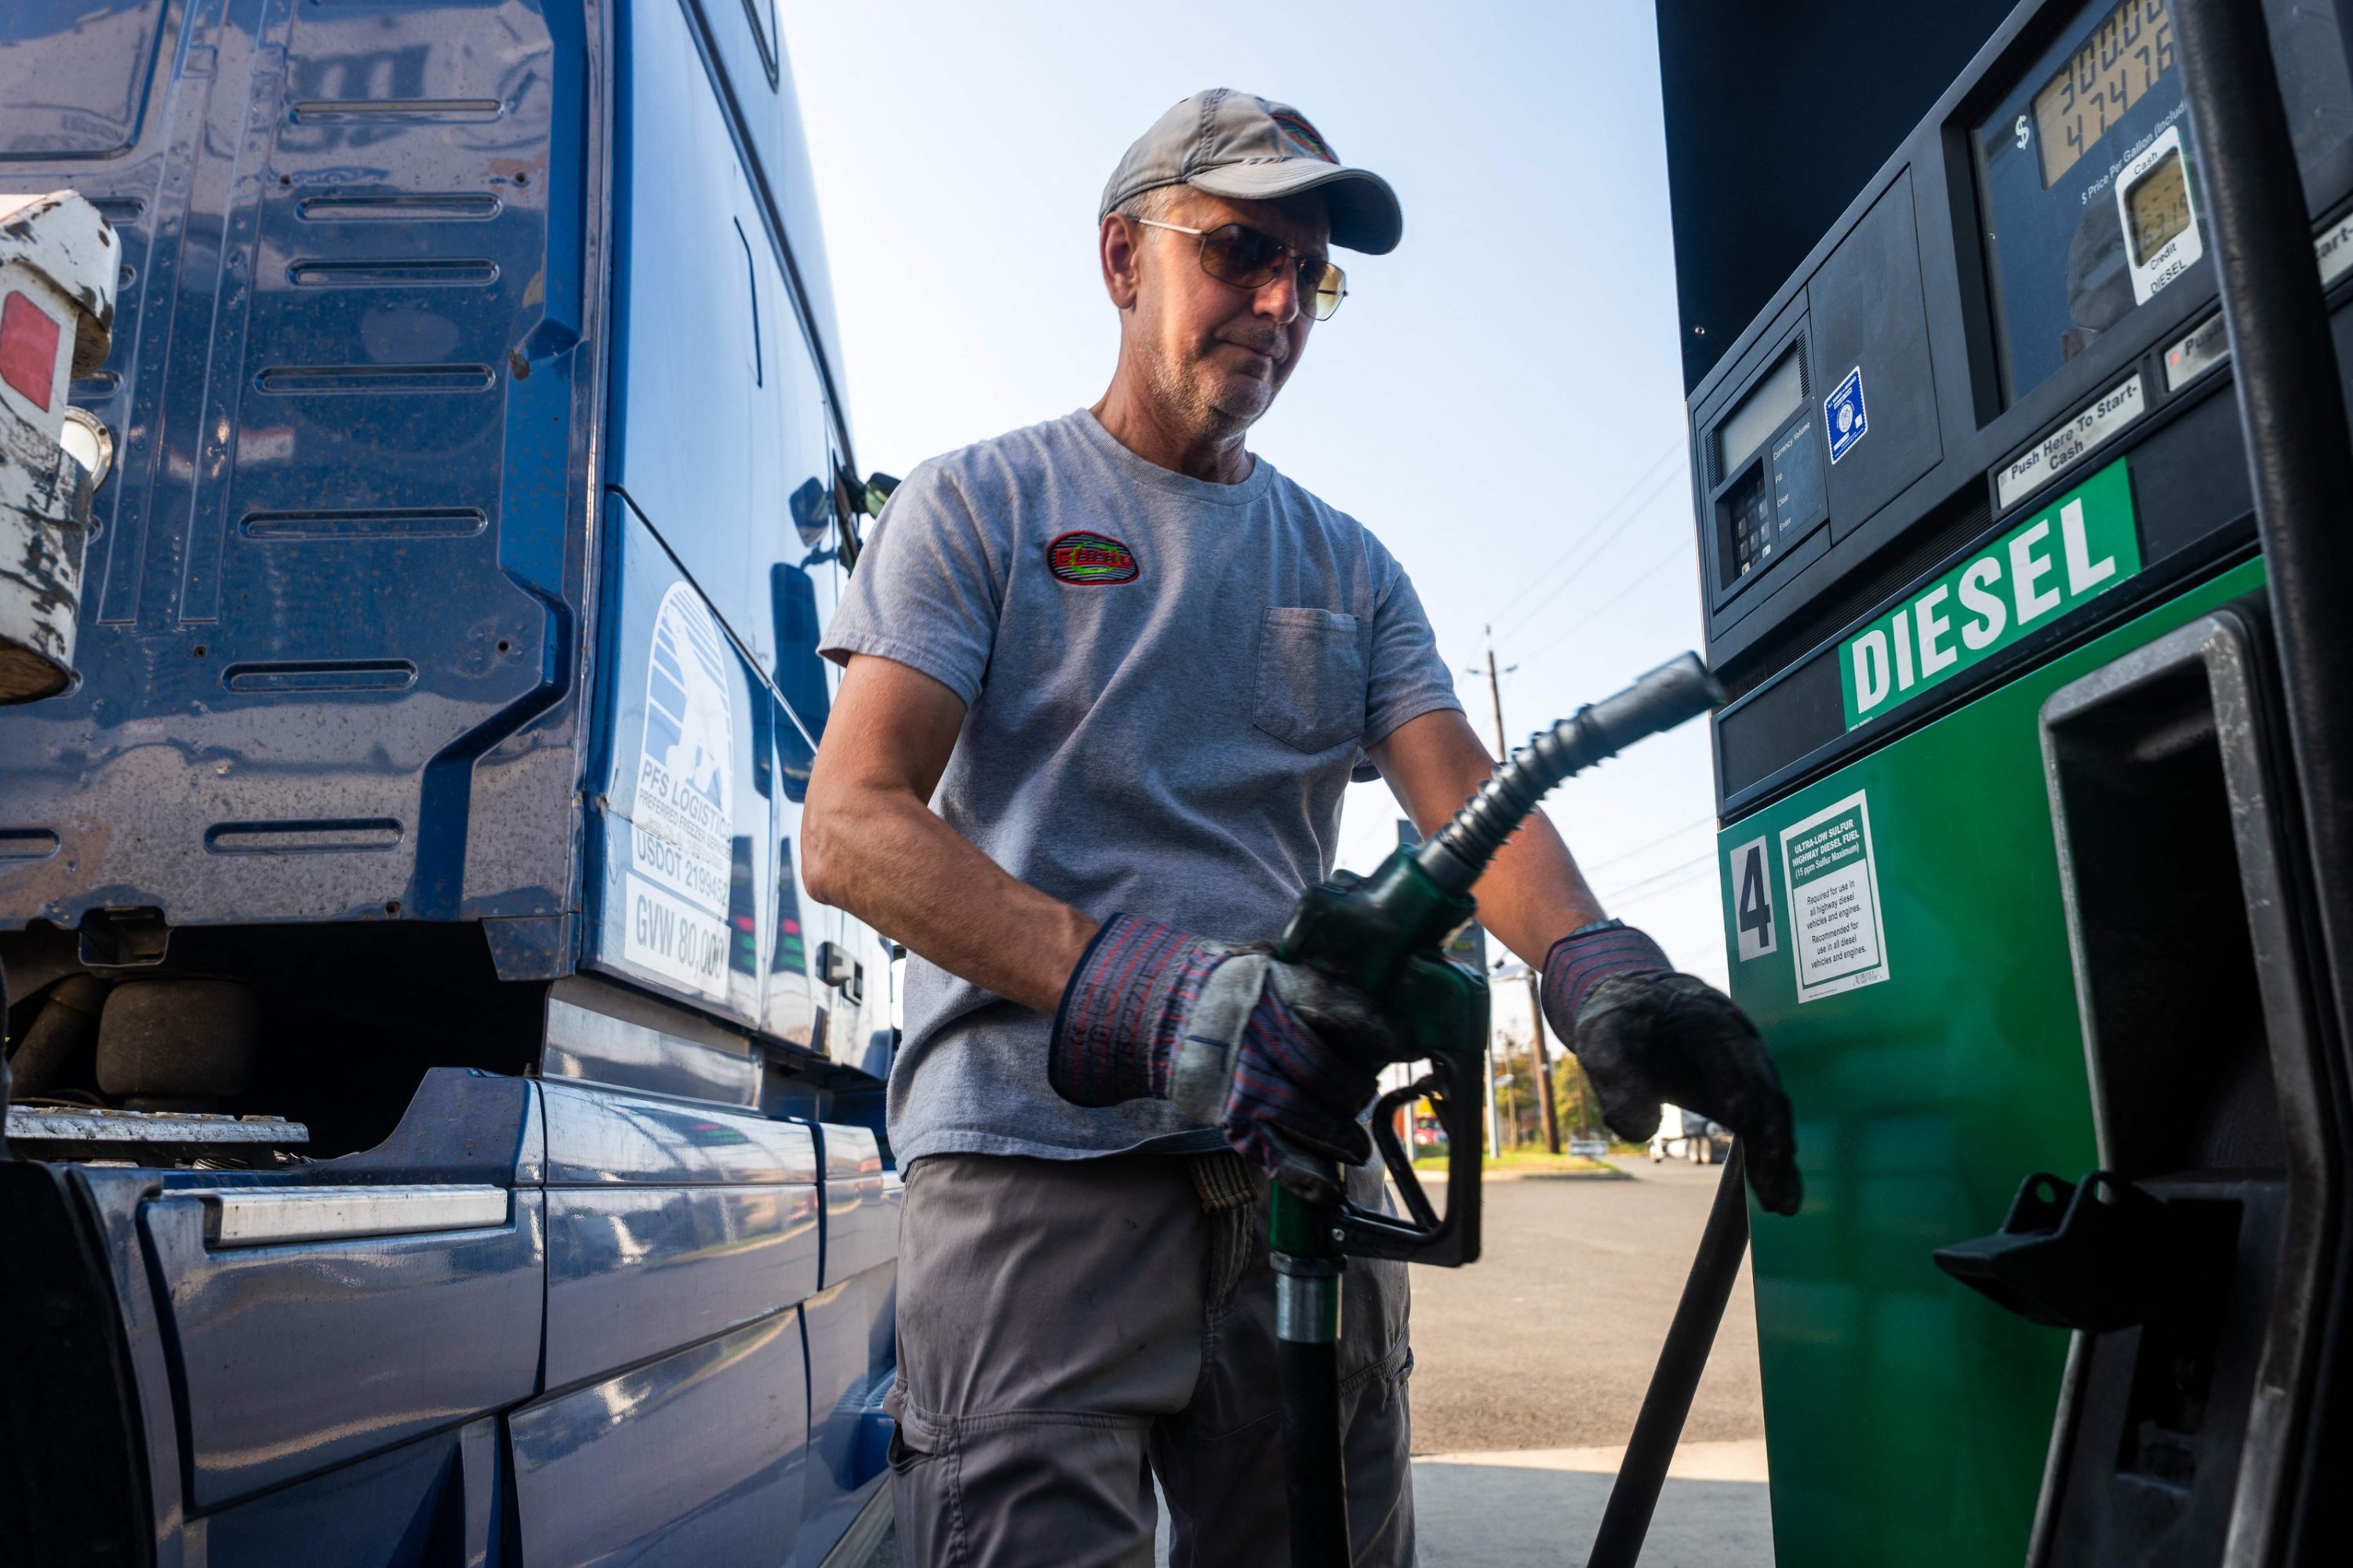
Following the call with Russian President Vladimir Putin on Oct. 9, U.S. President Donald Trump announced that Russia would immediately supply more than 300,000 metric tons of diesel to the U.S. and global markets. The initial volume of 300,000 metric tons is equivalent to approximately 2.25 million barrels. However, the announced volumes should not be treated as deliveries that have already taken place. They represent volumes that Russia has pledged or is expected to supply.
Another central question surrounding the U.S. move to source diesel from Russia is how much the announced volumes could ease the country’s supply shortfall. According to an analysis published by S&P Global Commodity Insights on Oct. 12, Russian diesel exports had recently remained in the range of 100,000 to 150,000 barrels per day. However, it remains unclear whether Russia can supply the announced volumes in addition to its existing exports.
According to S&P Global’s seaborne trade data dated Sept. 29, Russia exported 713,000 metric tons of diesel and gasoil by sea in July 2026 and 535,000 metric tons in August. The total fell to 448,000 metric tons between Sept. 1 and Sept. 24. No diesel or gasoil shipments departed from Black Sea ports during the week ending Sept. 24, while Russia’s total seaborne exports fell to 81,000 metric tons that week. Russian shipments may therefore prove insufficient to significantly ease price pressures in U.S. and global markets in the short term. The scale of the impact will depend on how much of the announced volume is actually shipped and the extent to which Russian refineries are able to recover their production capacity.
Europe, Türkiye in equation
The U.S. decision to license Russian diesel raises questions for Europe not only about tight supply in petroleum product markets but also about the consistency of sanctions targeting Russian energy. Additional diesel shipments from Russia could provide limited relief to markets, while the decision could also influence the debate over how far Europe can sustain its policy toward Russian energy resources amid pressure on energy supplies and costs.
Natural gas storage is a particular concern in Europe, where some countries are struggling to meet storage targets. According to a blog post by Richard Pratt published by RBN Energy on Oct. 8, natural gas storage facilities across the European Union were slightly more than 70% full, while Germany’s storage facilities were at 59%. Germany accounts for approximately 22% of the EU’s total natural gas storage capacity, making its low storage level significant for Europe’s broader energy security.
Pressure from rising energy costs and declining industrial competitiveness in Germany could bring the prospect of a return to Russian gas back onto the political agenda. While Chancellor Friedrich Merz maintains Europe’s firm political stance toward Russia, figures such as Alice Weidel, co-leader of the Alternative for Germany (AfD) party, advocate a different approach. Weidel has called for the lifting of the ban on Russian energy imports and the resumption of natural gas supplies through the damaged Nord Stream 2 pipeline. This situation can be interpreted as a kind of “good cop, bad cop” dynamic in Germany’s energy policy toward Russia. If pressure from rising energy costs intensifies, the possibility of a return to Russian gas could once again become a subject of debate in European politics.
Türkiye is also among the countries that must manage the economic and geopolitical dimensions of energy policy toward Russia simultaneously. While Ankara continues to import pipeline gas from Russia, it is seeking to diversify its sources and expand its liquefied natural gas (LNG) portfolio.
The Oct. 16 meeting in Moscow between Türkiye’s Minister of Energy and Natural Resources, Alparslan Bayraktar, and Alexey Miller, chairperson of Gazprom, shows that natural gas cooperation between the two countries remains on the agenda. Following the meeting, Bayraktar said that all aspects of their longstanding cooperation in natural gas had been discussed and that new opportunities to advance the partnership had been evaluated. However, this statement does not indicate that existing contracts have been renewed or that supply terms beyond 2027 have been finalized. While uncertainty remains over the terms under which long-term gas contracts will continue, Türkiye may continue purchasing Russian gas through short-term contracts or periodic agreements. Price competitiveness, domestic demand, conditions in the LNG market and Ankara’s supply diversification strategy will all play a decisive role in this process.
Of course, the temporary authorization for Russian diesel imports into the U.S. and Türkiye’s continued procurement of Russian gas cannot be assessed within the same legal and political framework. Nevertheless, these examples show that energy policy is shaped by more than political preferences alone. Countries are trying to balance sanctions, security of supply, prices and industrial needs.
The broader significance of “From Russia, with love” for energy markets lies here. Even as geopolitical competition intensifies, security of supply and cost pressures can reopen debate over the terms of trade with Russian energy suppliers. The temporary authorization granted by the U.S. for Russian diesel, the debate over a return to Russian gas in Europe, and the flexibility in Türkiye’s supply policy are different examples, but all point to the tension between political objectives and the economic realities of the market.
The views and opinions expressed in this article are solely those of the author. They do not necessarily reflect the editorial stance, values or position of Daily Sabah. The newspaper provides space for diverse perspectives as part of its commitment to open and informed public discussion.
DAILYSABAH
هلدینگ کاسپین استانبول | خرید ملک در ترکیه | صرافی معتبر ایرانی در ترکیه | خرید و فروش طلا در ترکیه | مهاجرت به ترکیه | واردات و صادرات در ترکیه | نیازمندیهای ترکیه | اخبار ترکیه | اخبار جهانی | توریست ایران | خدمات توریستی در ایران | تورهای گردشگری ایران | هلدینگ اول | خدمات کاریابی و فریلنسری و شغل | مرجع اطلاعات ایران (همه چیز در ایران) | کیف پول و خدمات مالی و پرداخت یار | اخبار ایران | تابلو زنده قیمت ارز در ترکیه و استانبول | صرافی آنلاین ترکیه | قیمت طلا و نقره در ترکیه | سرمایه گذاری در ترکیه | جواهرات در ترکیه | نرخ لحظه ای ارزها در استانبول | قیمت دلار امروز در ترکیه | قیمت دلار استانبول امروز | قیمت لحظه ای دلار | اخبار روز ترکیه استانبول | اپلیکیشن ISTEX | اپلیکیشن قیمت لحظه ای دلار و یورو و لیر و ارزها در ترکیه
About the Author